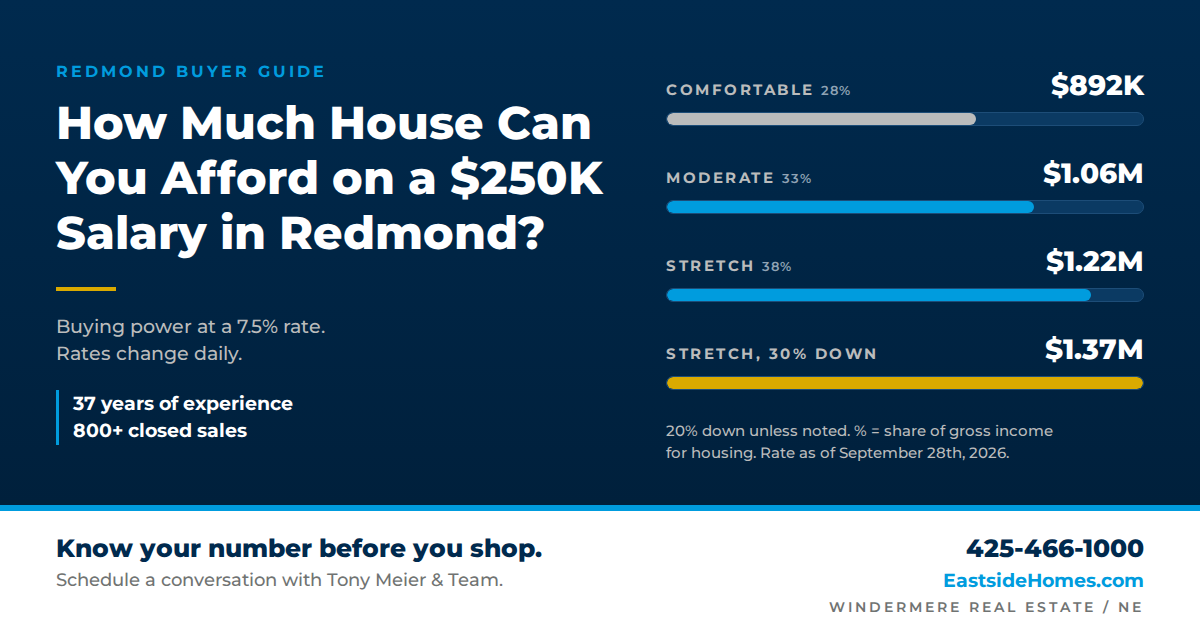
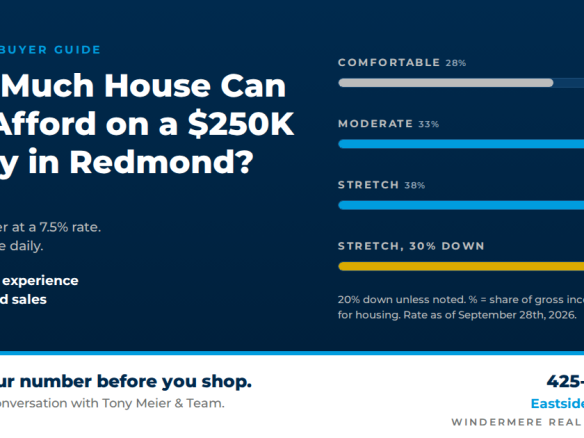
The short answer: with a $250,000 household salary, 20% down, and 30-year mortgage rates near 7.5%, most buyers can comfortably afford a Redmond home priced between about
$890,000 and $1.06 million. Buyers willing to stretch, or who bring a larger down payment, can reach roughly $1.2 million to $1.37 million.
Important: mortgage rates change daily. The figures in this post use a 7.5% rate as of September 28th, 2026. A half-point move in either direction shifts your buying power by roughly $50,000. Always get a current quote from a lender before you shop.
Our post on
what salary is considered upper class in Washington is one of the most-read pages on our site. This is the natural next question: what does that income actually buy on the Eastside?
How Lenders Size Your Budget
Lenders look at your gross monthly income and how much of it goes to housing. A $250,000 salary is about $20,833 per month before taxes. Three common benchmarks:
- Comfortable (28% of gross): about $5,833 per month for housing
- Moderate (33% of gross): about $6,875 per month
- Stretch (38% of gross): about $7,917 per month
Your total monthly housing cost includes principal, interest, property taxes, and homeowners insurance (plus HOA dues where they apply). Car loans, student loans, and other debt reduce how far a lender will let you go.
What $250K Buys in Redmond at 7.5%
Assumptions: 30-year fixed at 7.5%, property tax estimated at 0.9% of value per year, homeowners insurance about $175 per month, no HOA, no other significant debt.
| Budget Level |
20% Down |
30% Down |
| Comfortable (28%) |
$892,000 |
$1,002,000 |
| Moderate (33%) |
$1,056,000 |
$1,187,000 |
| Stretch (38%) |
$1,220,000 |
$1,372,000 |
Example: at the moderate level with 20% down, a $1,056,000 home means a loan of about $845,000. At 7.5%, principal and interest run about $5,908 per month, plus roughly $792 in property taxes and $175 in insurance, for a total near $6,875.
How Much Rates Matter
Here's the same moderate budget (33% of gross, 20% down) at three rates:
| Rate |
Home Price You Can Afford |
| 6.5% |
$1,154,000 |
| 7.0% |
$1,103,000 |
| 7.5% |
$1,056,000 |
Every half point is worth about $50,000 in purchase price. That's why we suggest locking in a pre-approval, then re-checking your numbers as you get closer to writing an offer.
What Changes the Answer for Tech Buyers
Base salary is only part of the picture for many Microsoft, Google, and Meta employees. A few factors can move your number significantly:
- RSUs and bonuses. Many lenders will count vesting stock and bonus income, usually with a two-year history and evidence it will continue. Some also allow you to use vested shares for your down payment.
- A larger down payment. Moving from 20% to 30% down adds more than $100,000 in buying power at every budget level in the table above.
- Jumbo loan rules. Most loans at this price point are jumbo loans, which often require larger cash reserves (sometimes 6 to 12 months of payments) and stronger credit.
- No state income tax. Washington has no state income tax, so more of your paycheck is available for housing than in states like California.
- Other debt. A $900 car payment can reduce your purchase power by more than $100,000.
How This Compares to the Redmond Market
Here's where the Redmond market (NWMLS Area 550, Redmond/Carnation) stands as of September 27th, 2026, compared with one month and one year ago:
| Metric |
Now |
1 Month Ago |
1 Year Ago |
| Median list price (active listings) |
$1,425,000 |
$1,407,000 (now +1.3%) |
$1,375,000 (now +3.6%) |
| Median sold price (last 30 days) |
$1,148,000 |
$1,210,000 (now -5.1%) |
$1,372,500 (now -16.4%) |
| Active listings |
196 |
200 |
162 |
| 30-year fixed rate |
7.50% |
6.81% |
6.38% |
What this means for a $250K buyer: the median Redmond home sold for $1,148,000 over the past 30 days. That sits between the moderate ($1,056,000) and stretch ($1,220,000) budgets above, so a $250K salary with 20% down reaches the middle of today's market.
Sold prices are running below last year. Monthly medians can swing with the mix of homes that close, so we also look at a longer window: the 90-day median sold price is $1,250,000, down 7.7% from $1,355,000 a year ago. At the same time, asking prices on active listings are up 3.6%, and there are 21% more homes for sale than a year ago. The gap between what sellers are asking and what buyers are paying, plus more inventory, gives well-prepared buyers more choice and more room to negotiate.
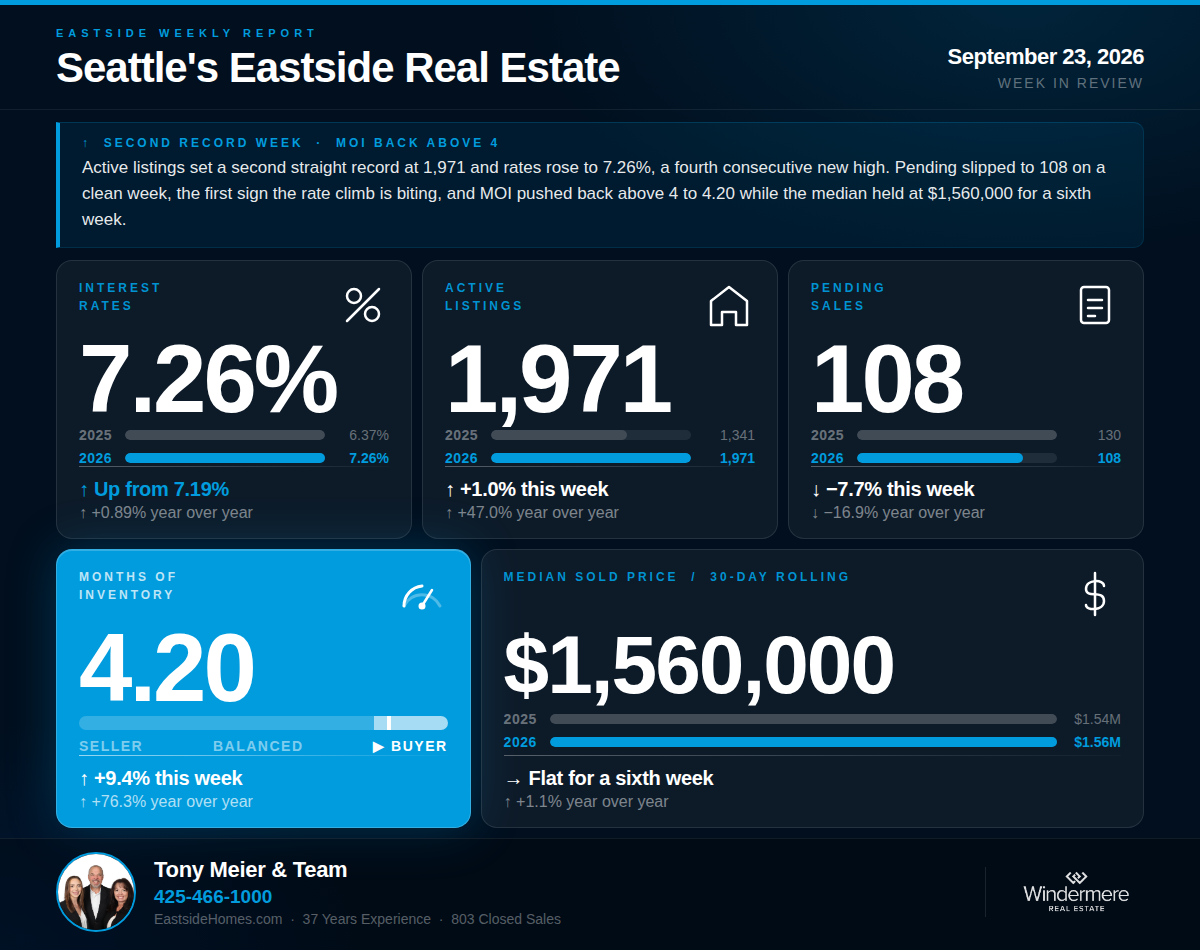
The flip side is rates. The 30-year fixed has climbed from 6.81% to 7.50% in the past month alone. For a $250K salary at the moderate budget, that one-month move cut buying power by roughly $65,000, which is why a current pre-approval matters.
Here's What I Suggest
- Talk to a lender first. Get a pre-approval based on today's rate and your complete income, including RSUs.
- Decide your comfort number, not just your maximum. The amount a lender approves is often higher than the payment you'll enjoy living with.
- Watch rates weekly. A small rate move can change which homes fit your budget.
- Let us show you what your budget buys today. We track every Redmond listing and sale and can show you where your number lands, street by street.
Ready to run your numbers? Contact Tony Meier & Team at
425-466-1000 or visit
EastsideHomes.com.
Frequently Asked Questions
How much house can I afford on a $250,000 salary?
At a 7.5% rate with 20% down and little other debt, most buyers can comfortably afford about $890,000 to $1.06 million, and up to about $1.22 million at a stretch. Rates change daily, so confirm with a lender.
Is $250,000 a good salary for buying a home in Redmond?
Yes. With 20% down, it reaches the middle of the current Redmond market, where the median home sold for $1,148,000 over the past 30 days. RSUs, bonuses, or a larger down payment open up more.
Do lenders count RSUs as income?
Many do, typically with a two-year vesting history and documentation that the stock will continue to vest. Requirements vary by lender.
How much does a 1% rate change affect what I can afford?
On a $250,000 salary with 20% down, a 1% rate drop adds roughly $100,000 in buying power.
What is the 28% rule?
It's a guideline that your monthly housing costs should stay at or below 28% of your gross monthly income. Many lenders will approve higher ratios.
This article is for general educational purposes and is not financial or lending advice. Estimates assume a 7.5% 30-year fixed rate as of September 28th, 2026, an estimated 0.9% annual property tax rate, and $175 per month for insurance. Actual rates, taxes, insurance, and loan approval vary by borrower and change daily. Consult a licensed mortgage professional for a personalized estimate. Market figures are for NWMLS Area 550 (Redmond/Carnation) residential listings as of September 27th, 2026; active list prices are as of the latest data feed. Mortgage rates are the Mortgage News Daily 30-year fixed index. Statistics not compiled or published by NWMLS.
Tony Meier & Team | Windermere Real Estate / NE | 425-466-1000 |
EastsideHomes.com