6 Min. Read
Audio Version
Tony Meier | Windermere Real Estate | 37 Years Experience | 808 Closed Eastside Sales
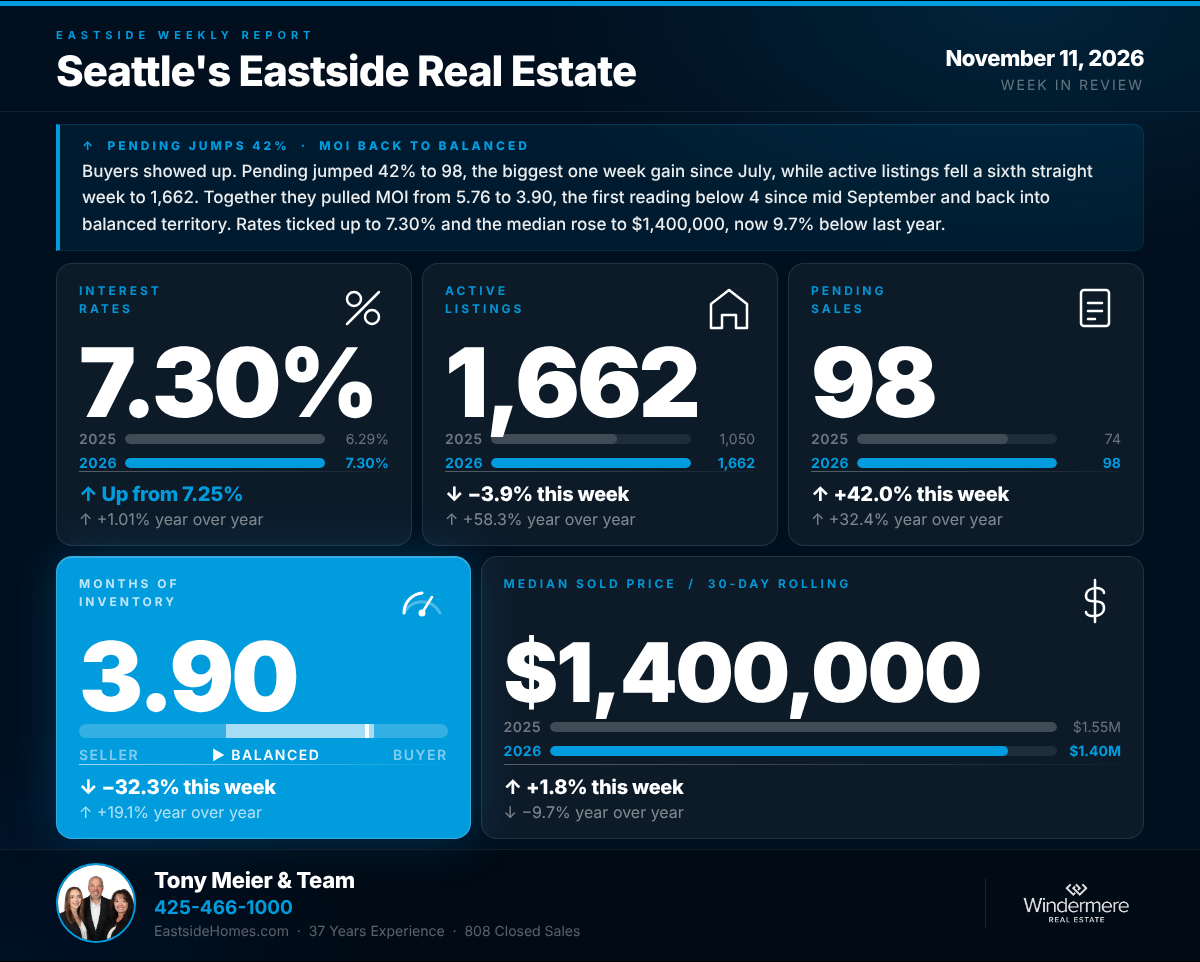
Lower rates finally brought buyers back, and then the rates went away. Daily mortgage rates touched 7.17% on November 5th and 6th, the lowest since late September, and pending sales jumped 42% to 98, the biggest one-week gain since July. With active listings down a sixth straight week to 1,662, months of inventory fell from 5.76 to 3.90, the first reading below 4 since mid-September. Then Tuesday's inflation report showed prices rising again, rates jumped 12 basis points in a day, and the week closed at 7.30%, above last week. Closings slowed to 71, and the rolling median rose to $1,400,000, 9.7% below a year ago.

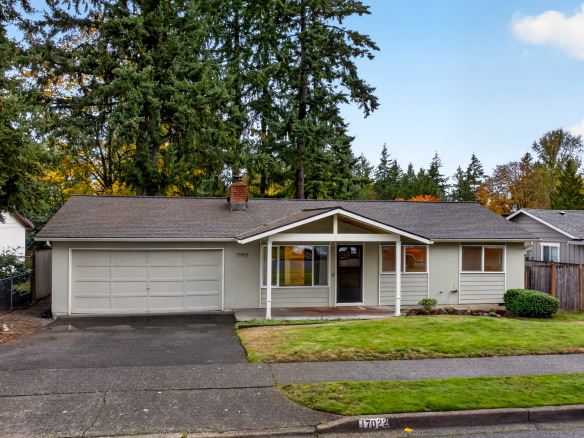
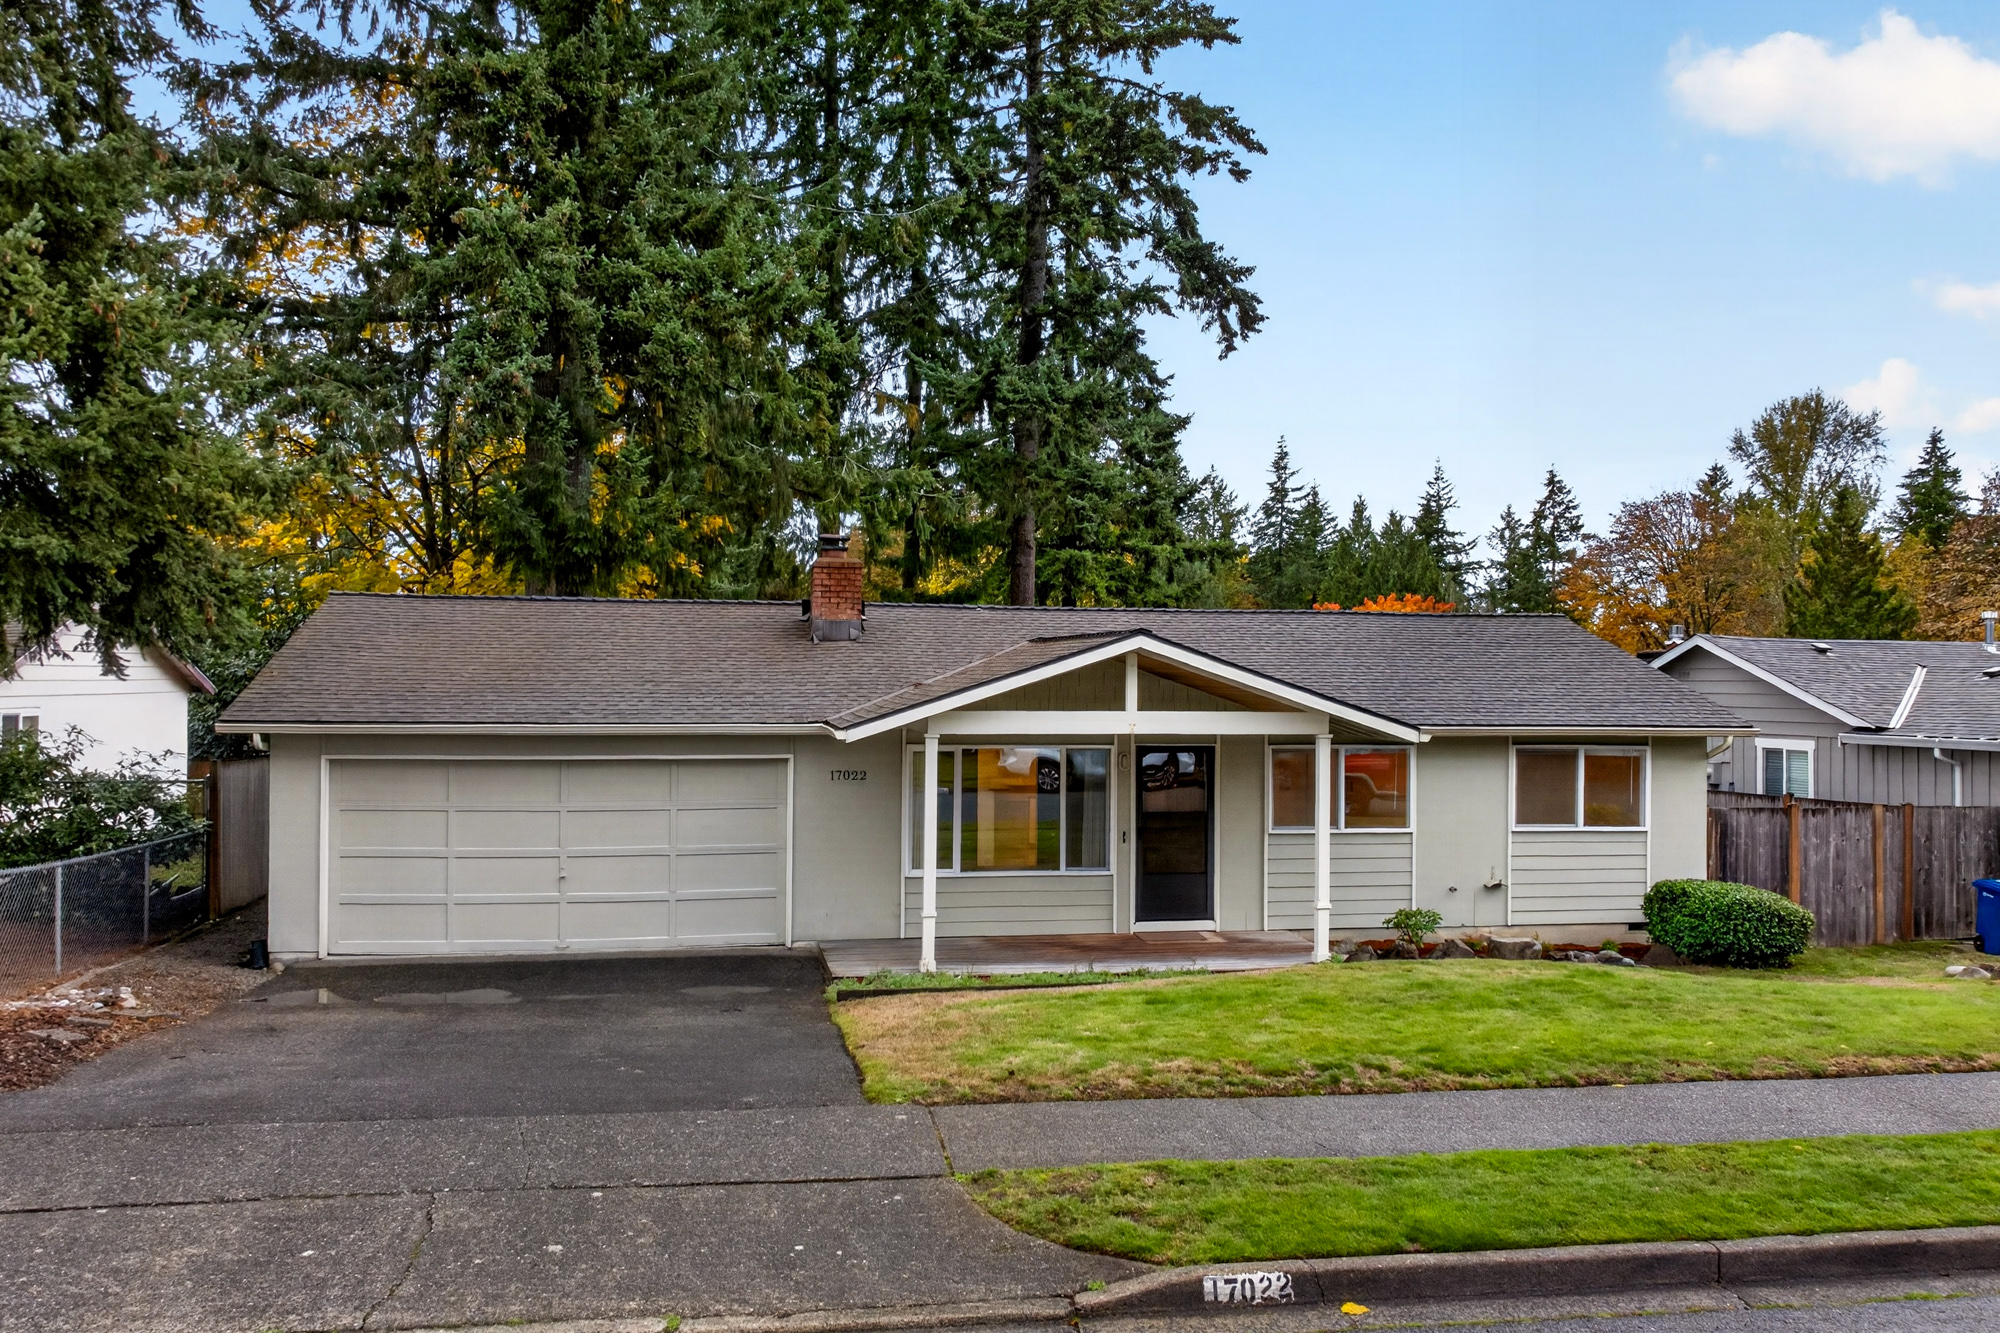
One Story in Redmond: 3 Bedrooms, 1 Full Bath, Fully Fenced Yard + Shed
17022 NE 106th St, Redmond Details
1 week ago
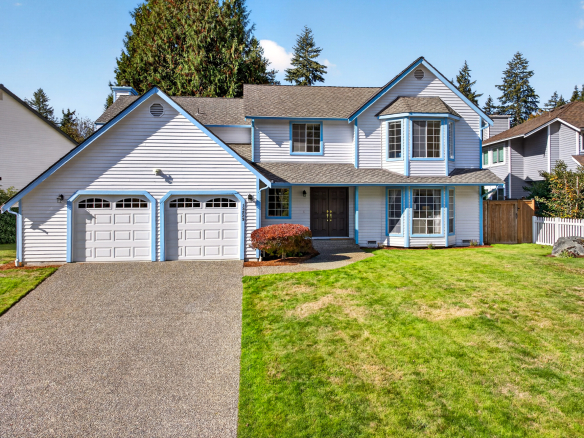
Redmond Two Story: 4 Bedrooms, Bonus Room, Central A/C, and a Private Fenced Yard in Northshore Schools
13229 174th Ave NE, Redmond Details
3 weeks ago
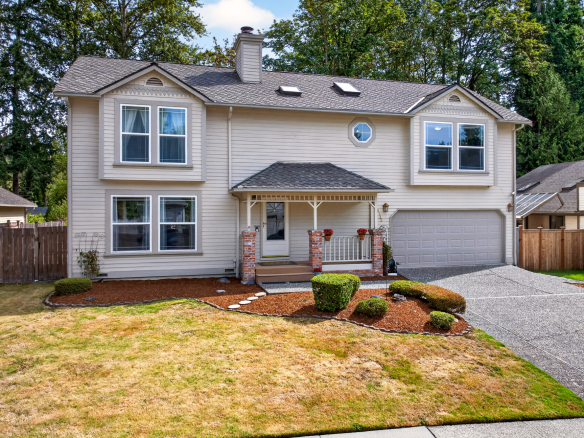
SOLD! Beautiful Redmond 4-Bedroom Home with Bonus Room Overlooking Greenbelt
13712 176th Ave NE, Redmond Details
2 months ago
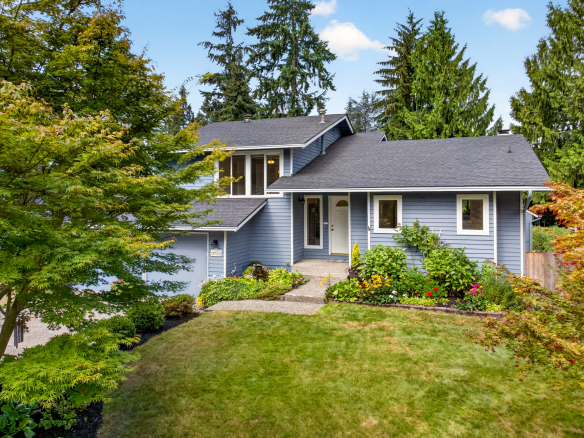
SOLD! Spacious Tri-Level Home with a Gardener’s Dream Yard on a Quiet Cul-de-Sac
2711 169th St SE, Bothell Details
2 months ago
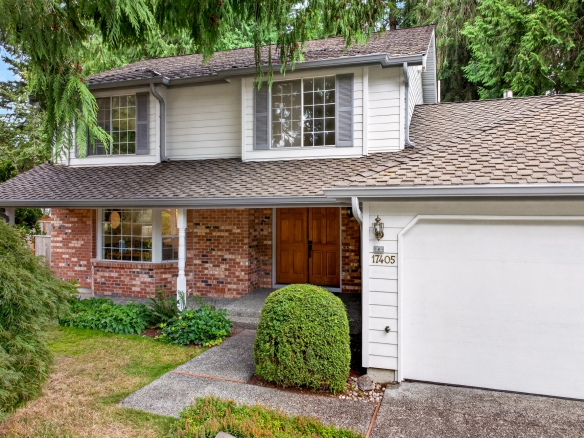
SOLD! Just Listed on English Hill in Redmond: Fully Remodeled Redmond Two Story
17405 NE 136th St, Redmond Details
2 months ago
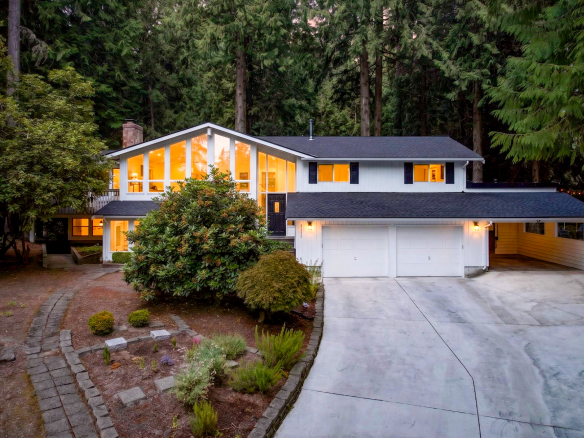
SOLD! Updated 3 Bedroom Plus Office/Den with MIL Space on 0.84 Private Acres in Woodinville
16224 195th Pl NE, Woodinville Details
3 months ago
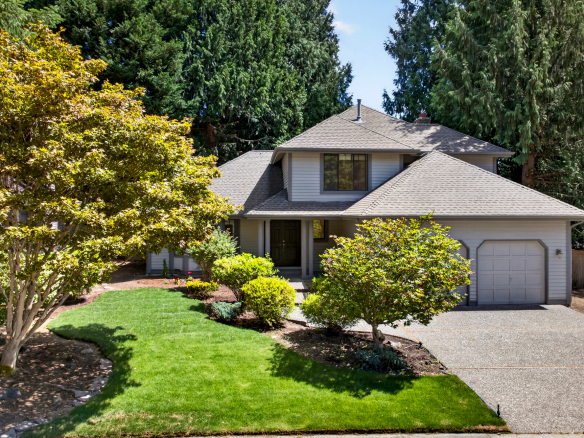
SOLD! Redmond Two Story, Fully Refreshed Inside and Out with Private Evergreen Backyard
13834 175th Pl NE, Redmond Details
3 months ago
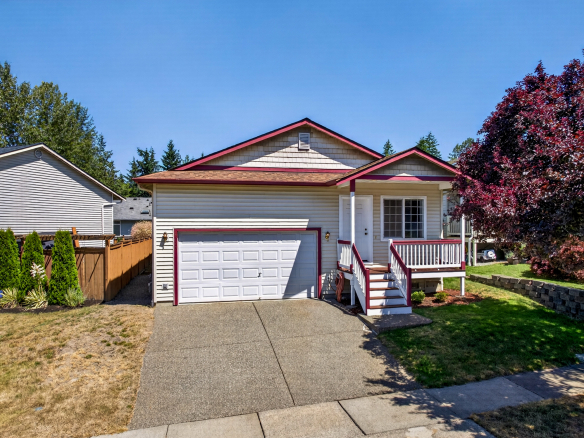
SOLD! Move-In Ready in Lynnwood: New Furnace, New Water Heater, Newer Roof
4223 147th St SW, Lynnwood Details
4 months ago
SOLD! Move-In Ready Condo in Lake Stevens: New Flooring, Updated Baths, Attached Garage
8916 Meridian Pl NE Unit A201, Lake Stevens Details
5 months ago
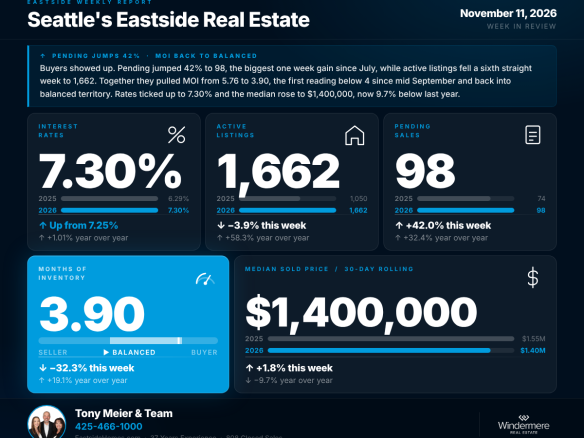
Daily rates fell to 7.17% and pending sales jumped 42% to 98, the biggest one-week gain since July, pulling MOI from 5.76 to 3.90. Then Tuesday's inflation report sent rates up 12 basis points in a day to 7.30%. Active listings fell a sixth week to 1,662 and the rolling median rose to $1,400,000, 9.7% below a year ago.
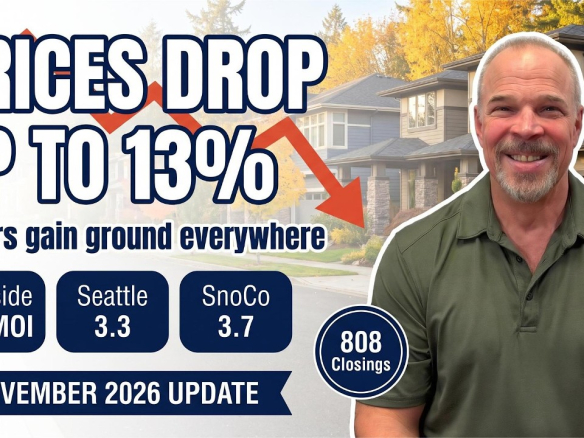
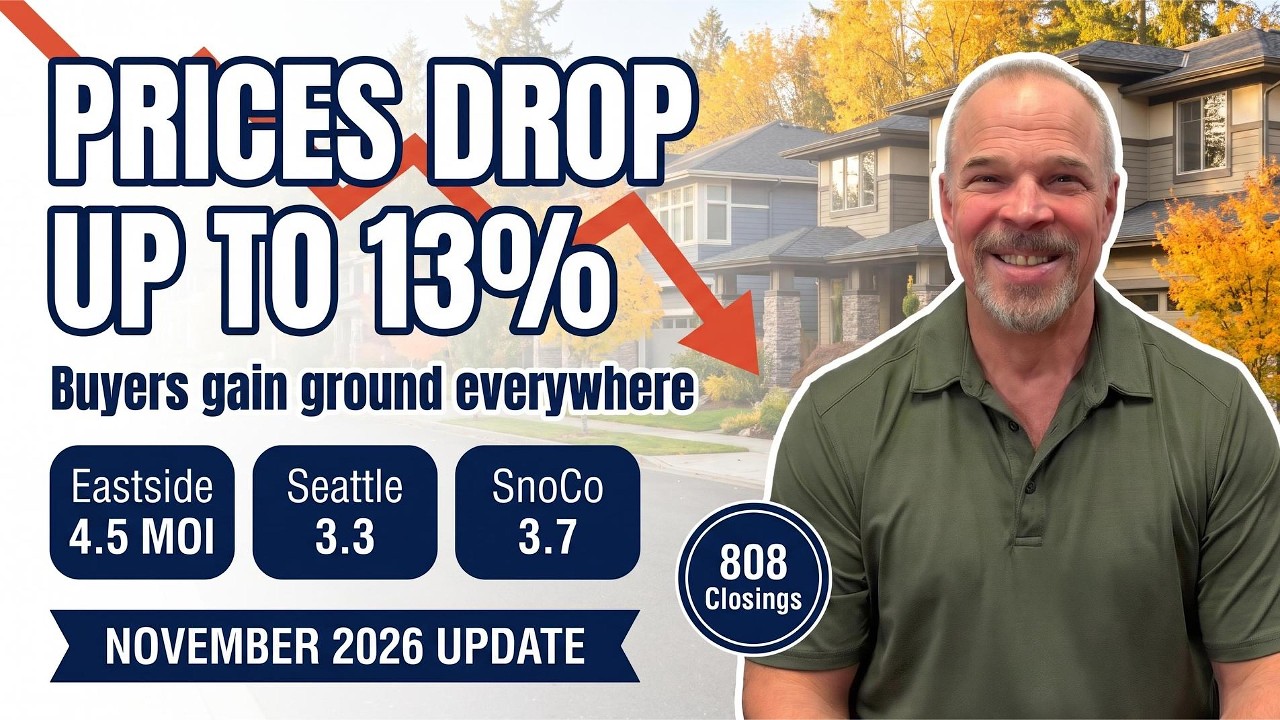
November 2026 Eastside, Seattle and Snohomish market update: MOI hits its highest October level since 2010 in all three markets, the Eastside median is down 12.90% year over year, and rates ease to 7.30%.
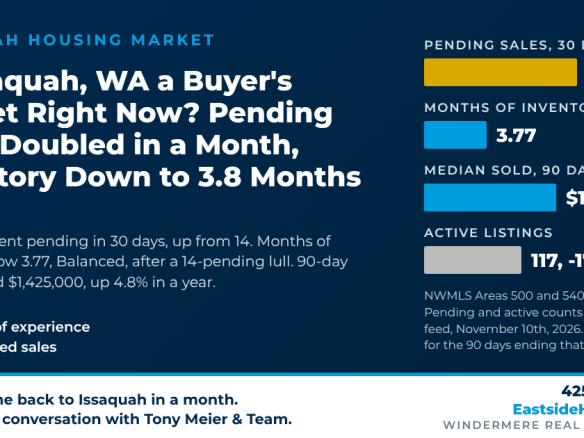
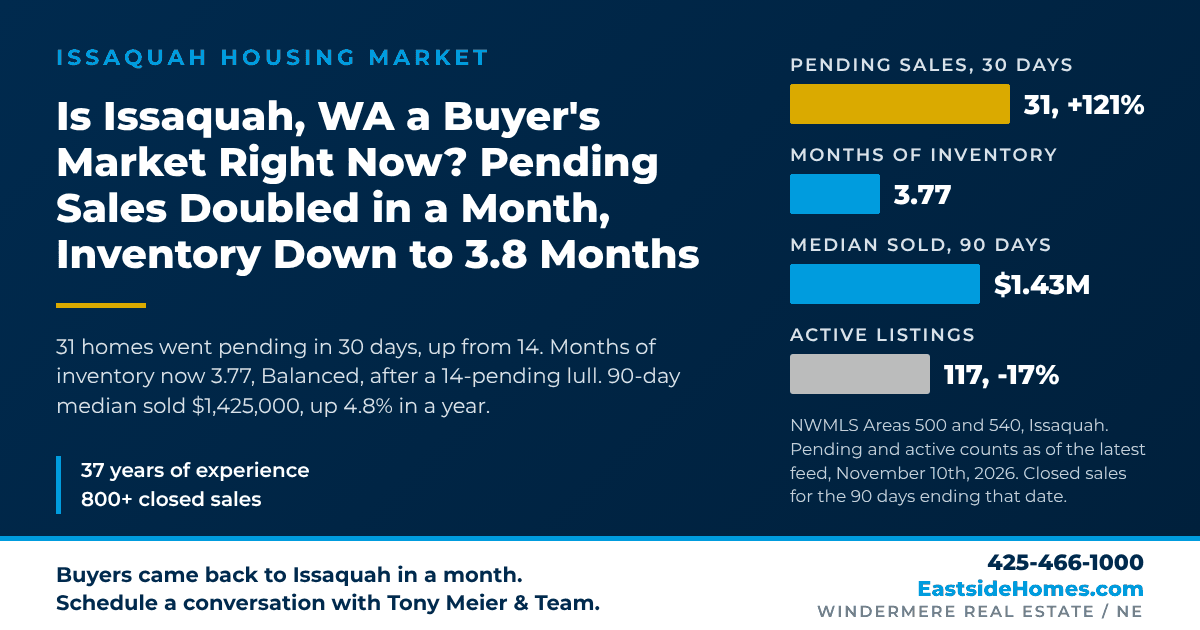
Issaquah pending sales doubled in a month and inventory fell to 3.77 months, now Balanced. 90-day median sold $1,425,000. Data as of November 10th, 2026.
Published on: November 5, 2026 Active listings rose 25.2% from a year earlier, giving buyers more...
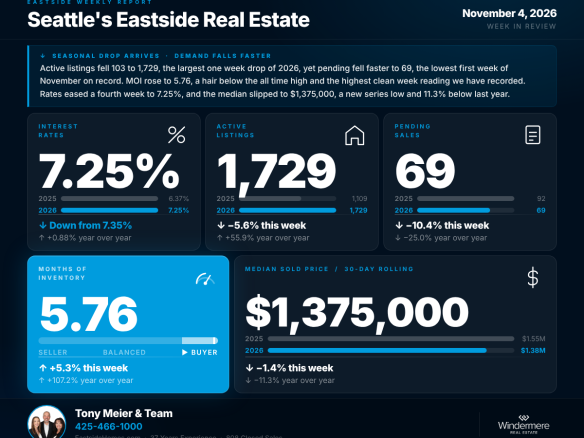
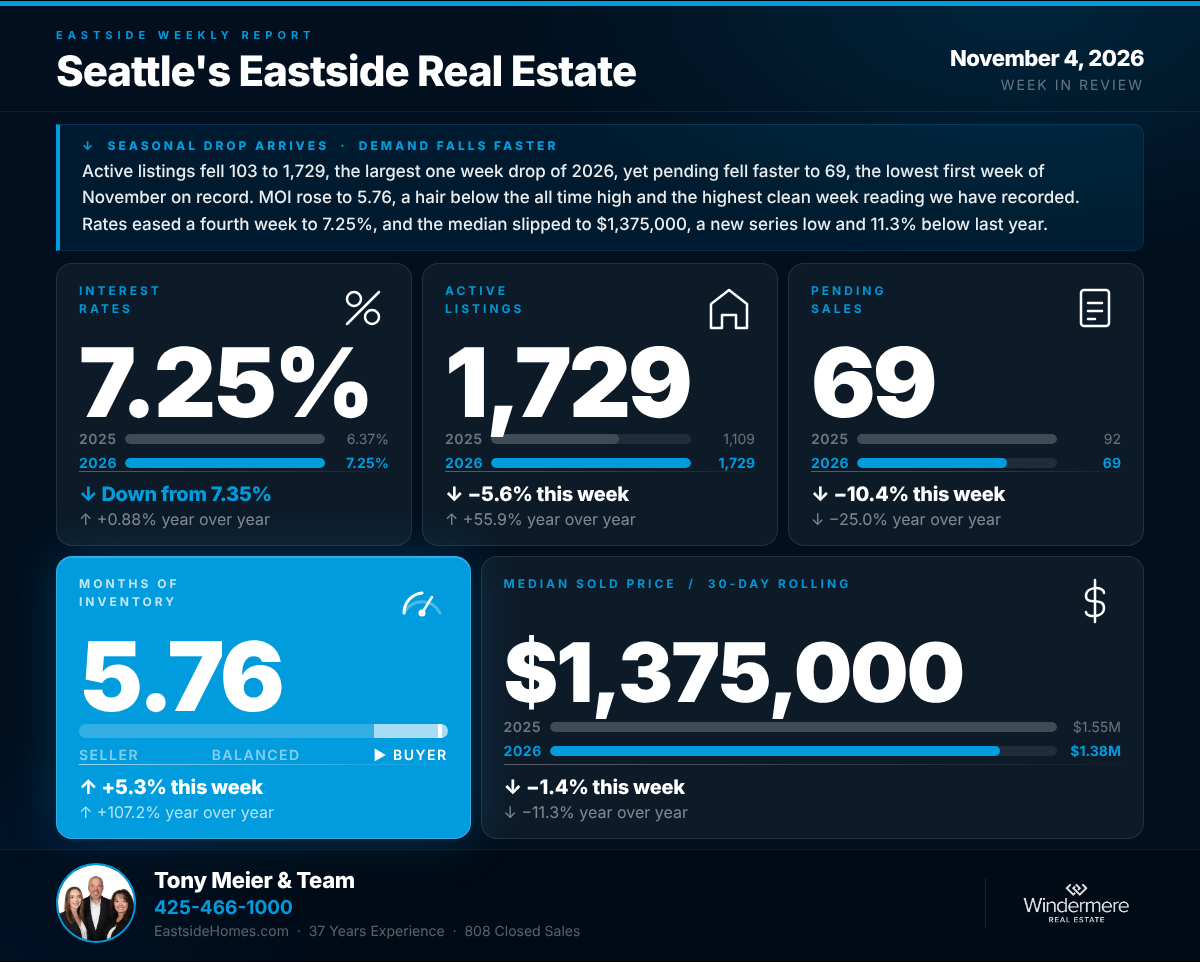
Rates eased a fourth straight week to 7.25% and active listings fell 5.6% to 1,729 as the November inventory decline arrived. Pending sales slipped to 69, MOI rose to 5.76, and the rolling median moved to $1,375,000, 11.3% below a year ago, giving buyers the widest window in years.
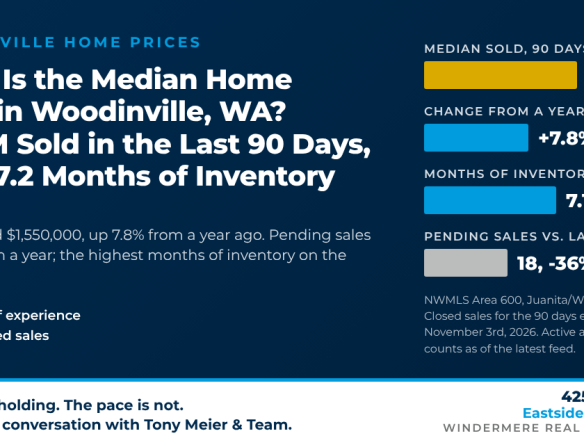
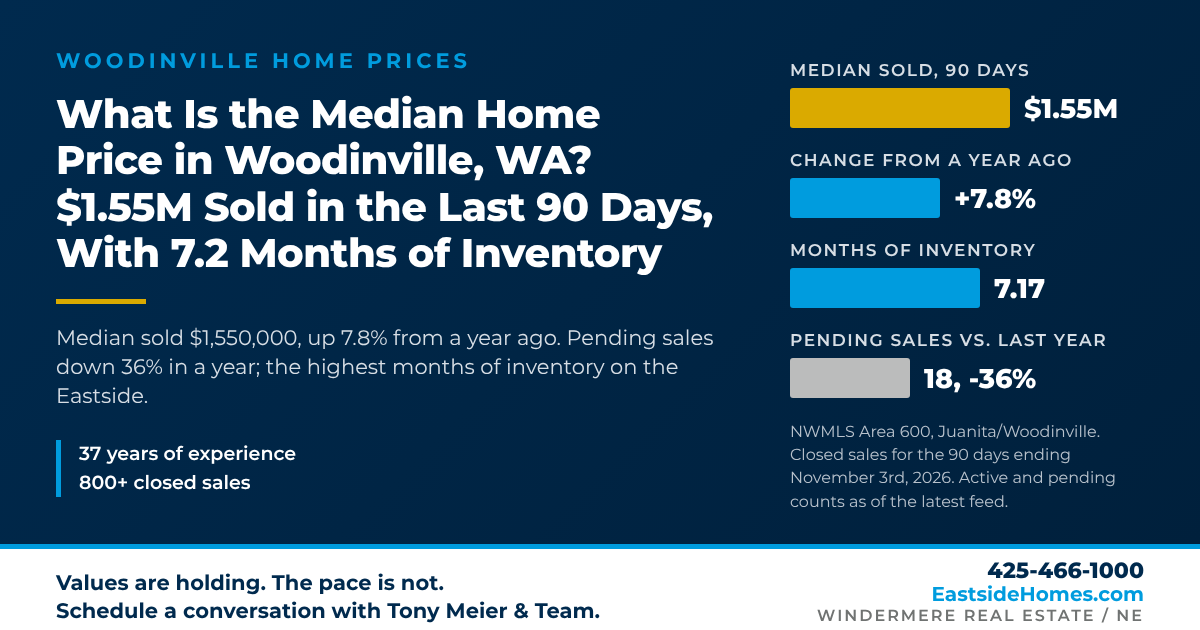
Woodinville's median sold price is $1,550,000 over the last 90 days, up 7.8% in a year, but pending sales are down 36% and inventory sits at 7.17 months.
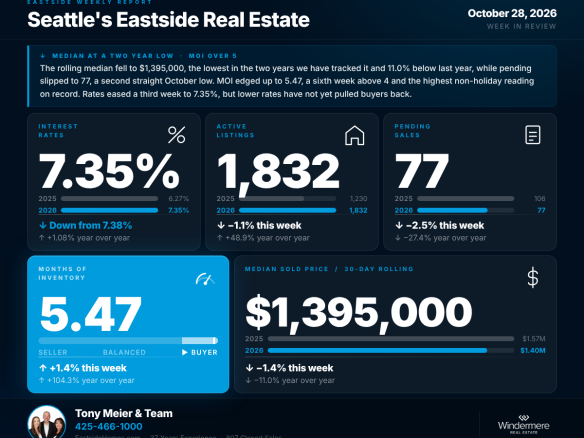
Pending sales slipped to 77, a second straight October low for our six-year series, while the rolling median fell to $1,395,000, the lowest in two years and 11.0% below last year. MOI reached 5.47, more than double a year ago, as rates eased a third week to 7.35% and active listings fell to 1,832.
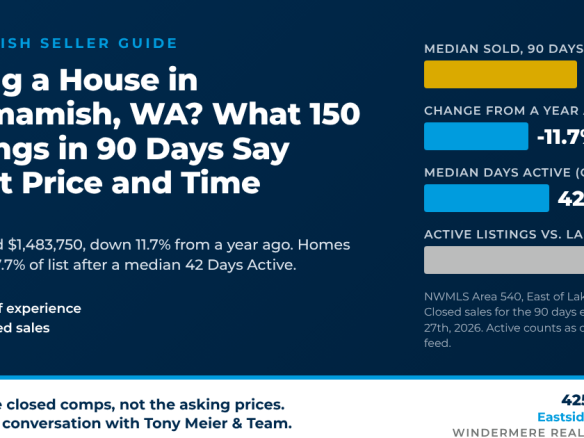
Sammamish median sold $1,483,750 over 90 days, down 11.7% from a year ago, at 97.7% of list after 42 Days Active. What sellers should price to now.
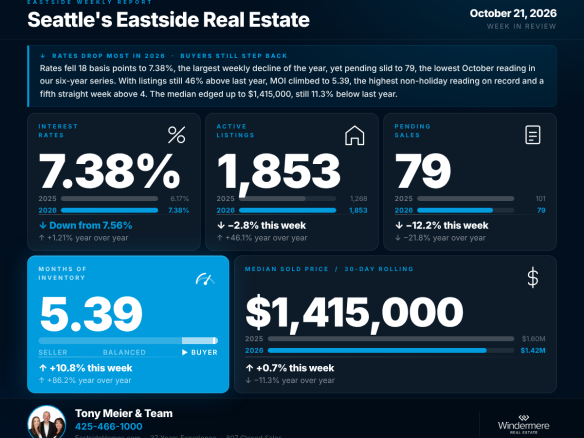
Rates dropped 18 bp to 7.38%, the biggest decline of 2026, yet pending sales fell to 79, the lowest October reading in our six-year series. MOI climbed to 5.39, a fifth straight week above 4, active listings fell to 1,853, and the rolling median sits at $1,415,000, 11.3% below a year ago.
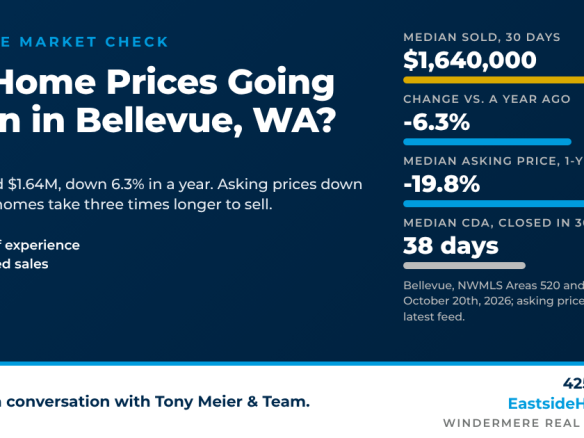
Bellevue median sold price is $1,640,000, down 6.3% in a year. Asking prices are down 19.8% and homes take 3x longer to sell. As of October 20th, 2026.
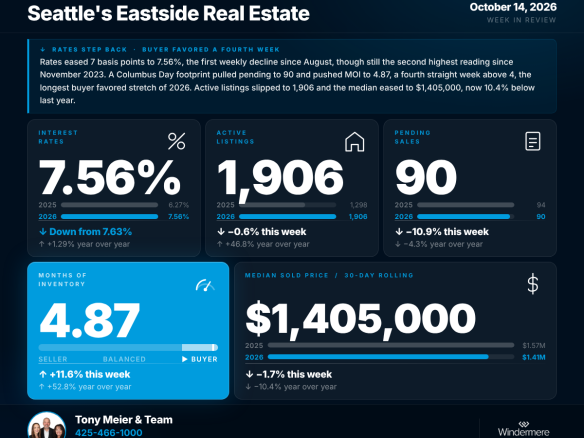
Rates eased 7 bp to 7.56%, the first decline since August 19th, while MOI rose to 4.87 for a fourth straight week above 4. Columbus Day week pulled pending to 90 and closings to 78, active listings slipped to 1,906, and the rolling median fell to $1,405,000, 10.4% below a year ago.
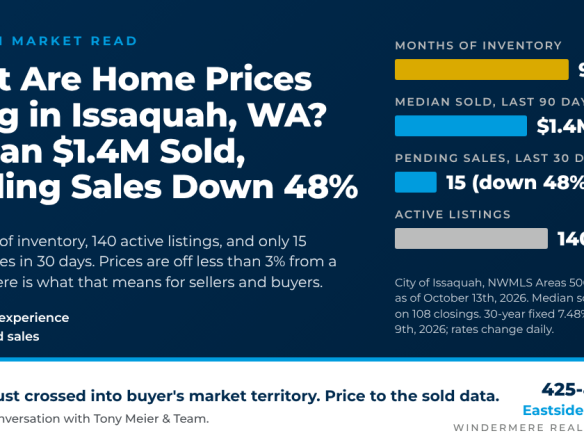
Issaquah's 90-day median sold price is $1,399,994, down 2.8% from a year ago, but pending sales fell 48% in a month and inventory hit 9.3 months.
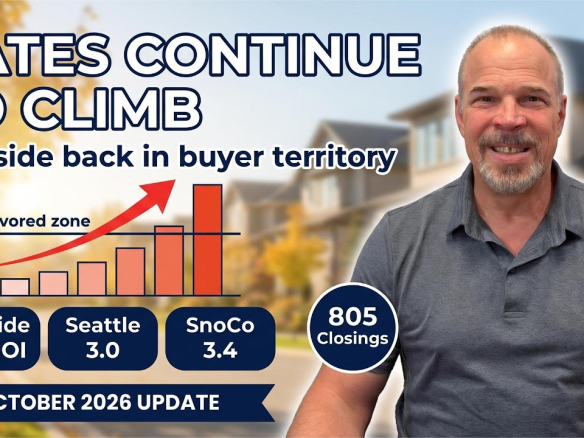
October 2026 Eastside, Seattle and Snohomish market update: rates jump to 7.59%, Eastside MOI hits 4.1 (buyer territory), and the Eastside median is down 9.52% year over year.
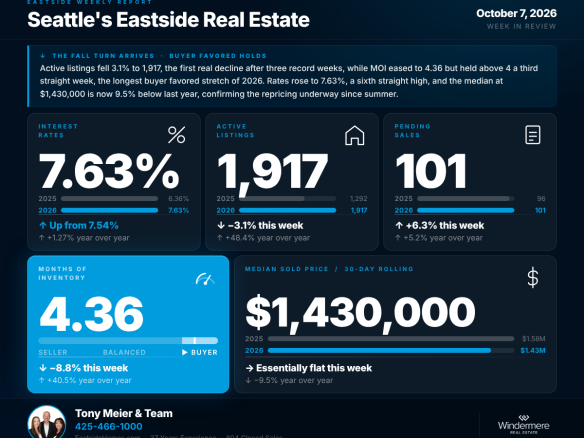
Active listings fell for the first time after three straight records, down 3.1% to 1,917, while pending sales rose to 101. MOI held above 4 for a third consecutive week, rates climbed to 7.63%, the highest since November 2023, and the rolling median sits 9.5% below a year ago at $1,430,000.
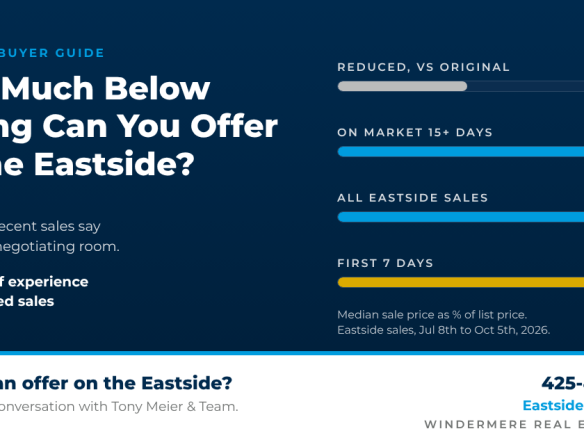
The typical Eastside home sells at 98.0% of list, but homes in their first week sell at full price while homes past 15 days sell near 96.6%. Here is how much room buyers really have, by area and price range.
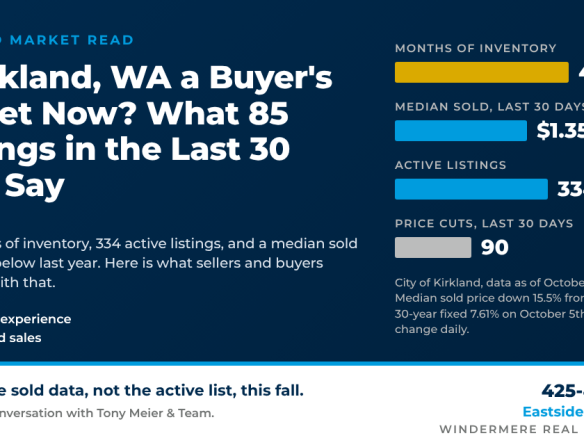
Kirkland hit 4.23 months of inventory on October 6th, 2026. Median sold $1,350,000, down 15.5% in a year. What sellers and buyers should do now.
Published on: October 6, 2026 Active listings increased 24.5% in September, while pending sales...
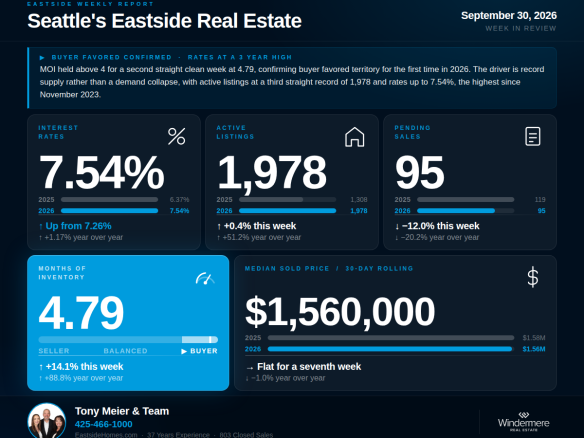
MOI held above 4 for a second consecutive clean week, the first time in 2026, confirming buyer-favored territory. Rates jumped to 7.54%, the highest since November 2023, and active listings set a third straight record at 1,978. Twenty years of NWMLS monthly data show the shift is driven by a return of supply, not a collapse in demand.
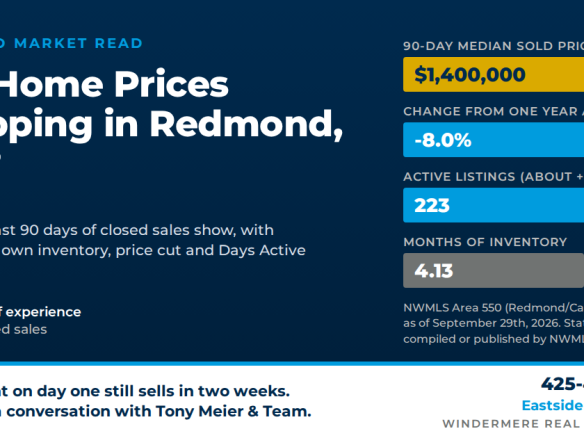
Redmond's 90-day median sold price is $1,400,000, down 8% from a year ago, while active listings are up about 76%. What it means for sellers and buyers.
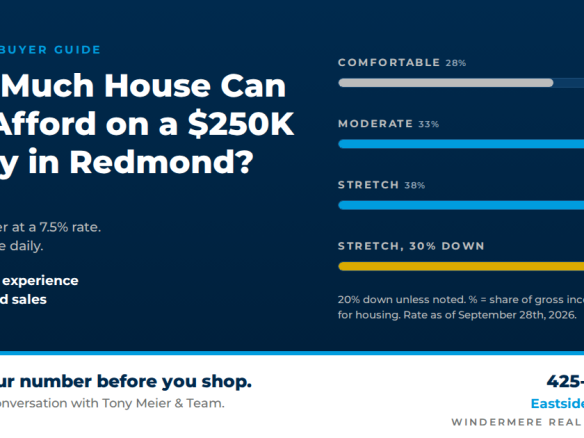
On a $250,000 salary with 20% down and rates near 7.5%, most buyers can comfortably afford a Redmond home between about $890,000 and $1.06 million. Here's the math, and what changes it.
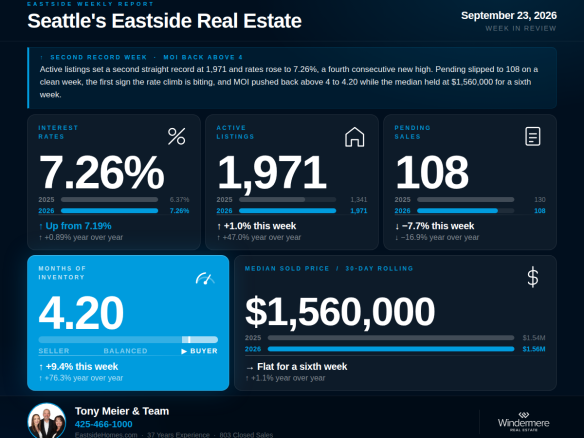
5 Min. Read Audio Version Tony Meier | Windermere Real Estate | 37 Years Experience |...
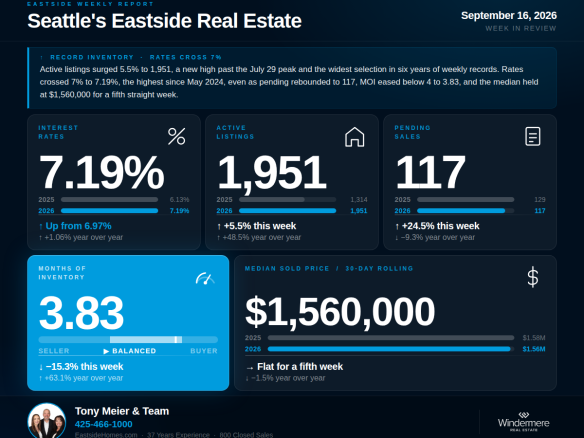
Active listings surged to 1,951, a new 2026 high seven weeks after the July peak and the highest weekly count in six years of tracking, while rates crossed 7% for the first time since May 2025, landing at 7.19%, up 1.06% year over year. Record selection meets the most expensive financing in 28 months.
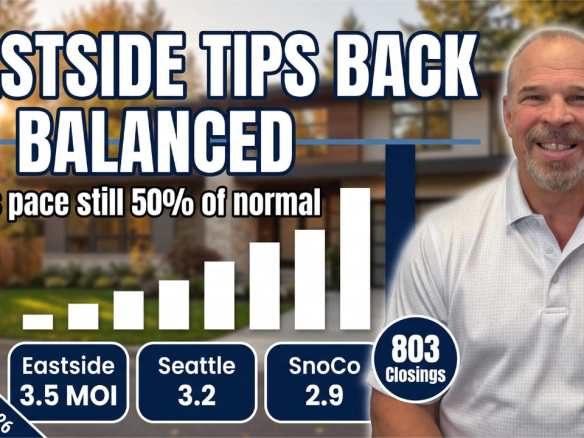
If you're a seasoned homeowner thinking about selling your current home and buying your next one,...
Published on: September 3, 2026 Northwest Multiple Listing Service (NWMLS) today released its...
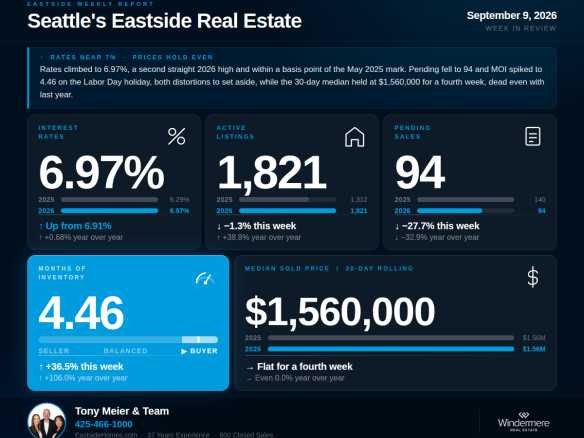
5 Min. Read Audio Version Last week we flagged that this reading would carry Labor Day...
Northwest MLS launches First Look September 4, 2026. How the new 21-day listing status works, what changed about days on market, and what it means for you.
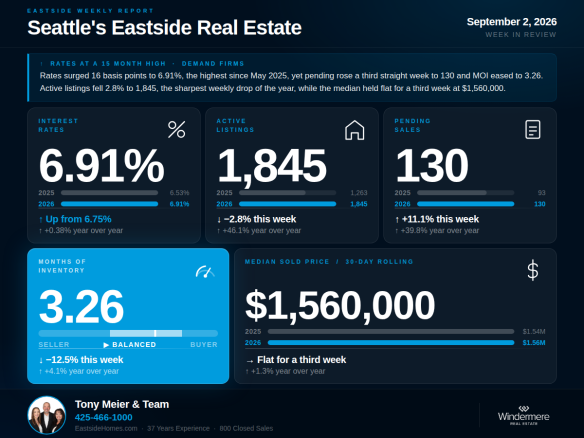
5 Min. Read Audio Version Tony Meier | Windermere Real Estate | 37 Years Experience | 800...
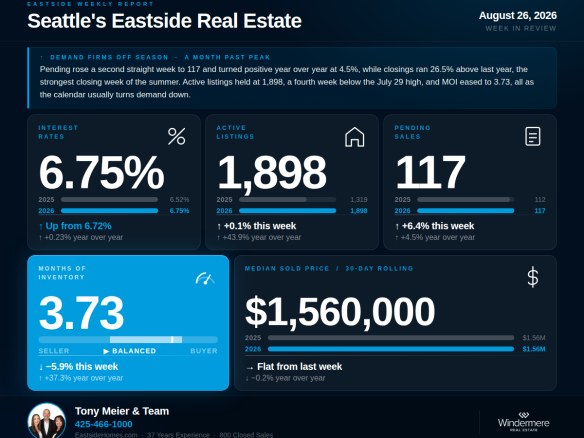
5 Min. Read Audio Version Tony Meier | Windermere Real Estate | 37 Years Experience | 800...
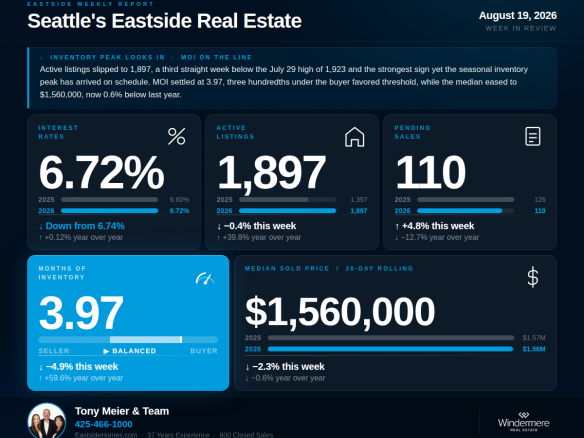
5 Min. Read Audio Version Tony Meier | Windermere Real Estate | 37 Years Experience | 800...
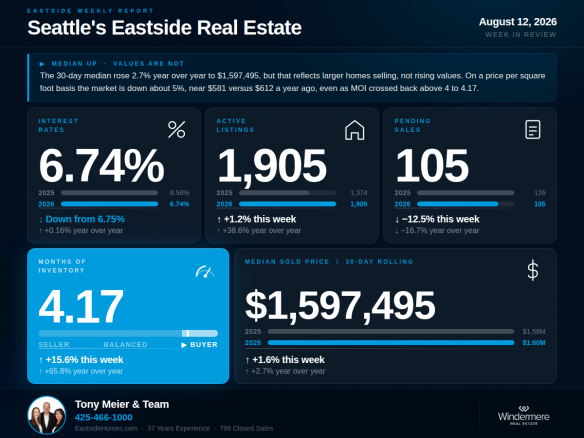
The 30-day median is up 2.7% year over year, but price per square foot is down about 5%. Larger homes are selling, masking a like-for-like value decline. Pending fell to 105, MOI crossed above 4 for the fifth time this year, and the inventory peak question remains open.
Tony & Team, we can't thank you enough for representing us in the sale of our home. Tony,...
Not every sale needs to be dramatic. Most of the work in a smooth transaction happens quietly, in...
When a market slows, the difference shows up in the details: how quickly you learn what buyers are...
Glenterra sellers Evan and Sarah Gilbertson share their experience selling with Tony Meier & Team.
Sunrise sellers Shilpa Nagde and Anurag Gomsale share their experience working with Tony Meier & Team.
We had an exceptional experience working with Tony Meier and team, and we couldn't be happier with...
When it was time to sell my house I decided to have Tony Meier and his team help me because many of...
I've worked with Tony on buying two houses and selling one. I've also worked with Tony when...
Thanks to Tony Meier & Team, we found our dream property in a great location! Then, with...

We had a fantastic experience working with Tony to sell our home. From the very beginning, Tony...
Tony is a consummate professional. If you want to sell your house quickly and at the maximum...
We had the pleasure of working with Tony and his team to sell our home in English Hill, and we...
I can hardly think of more demanding customers than the two of us, but Tony rose up to the...
Tony was exceptional in assisting us in the sale of our home in a very difficult market. He helped...
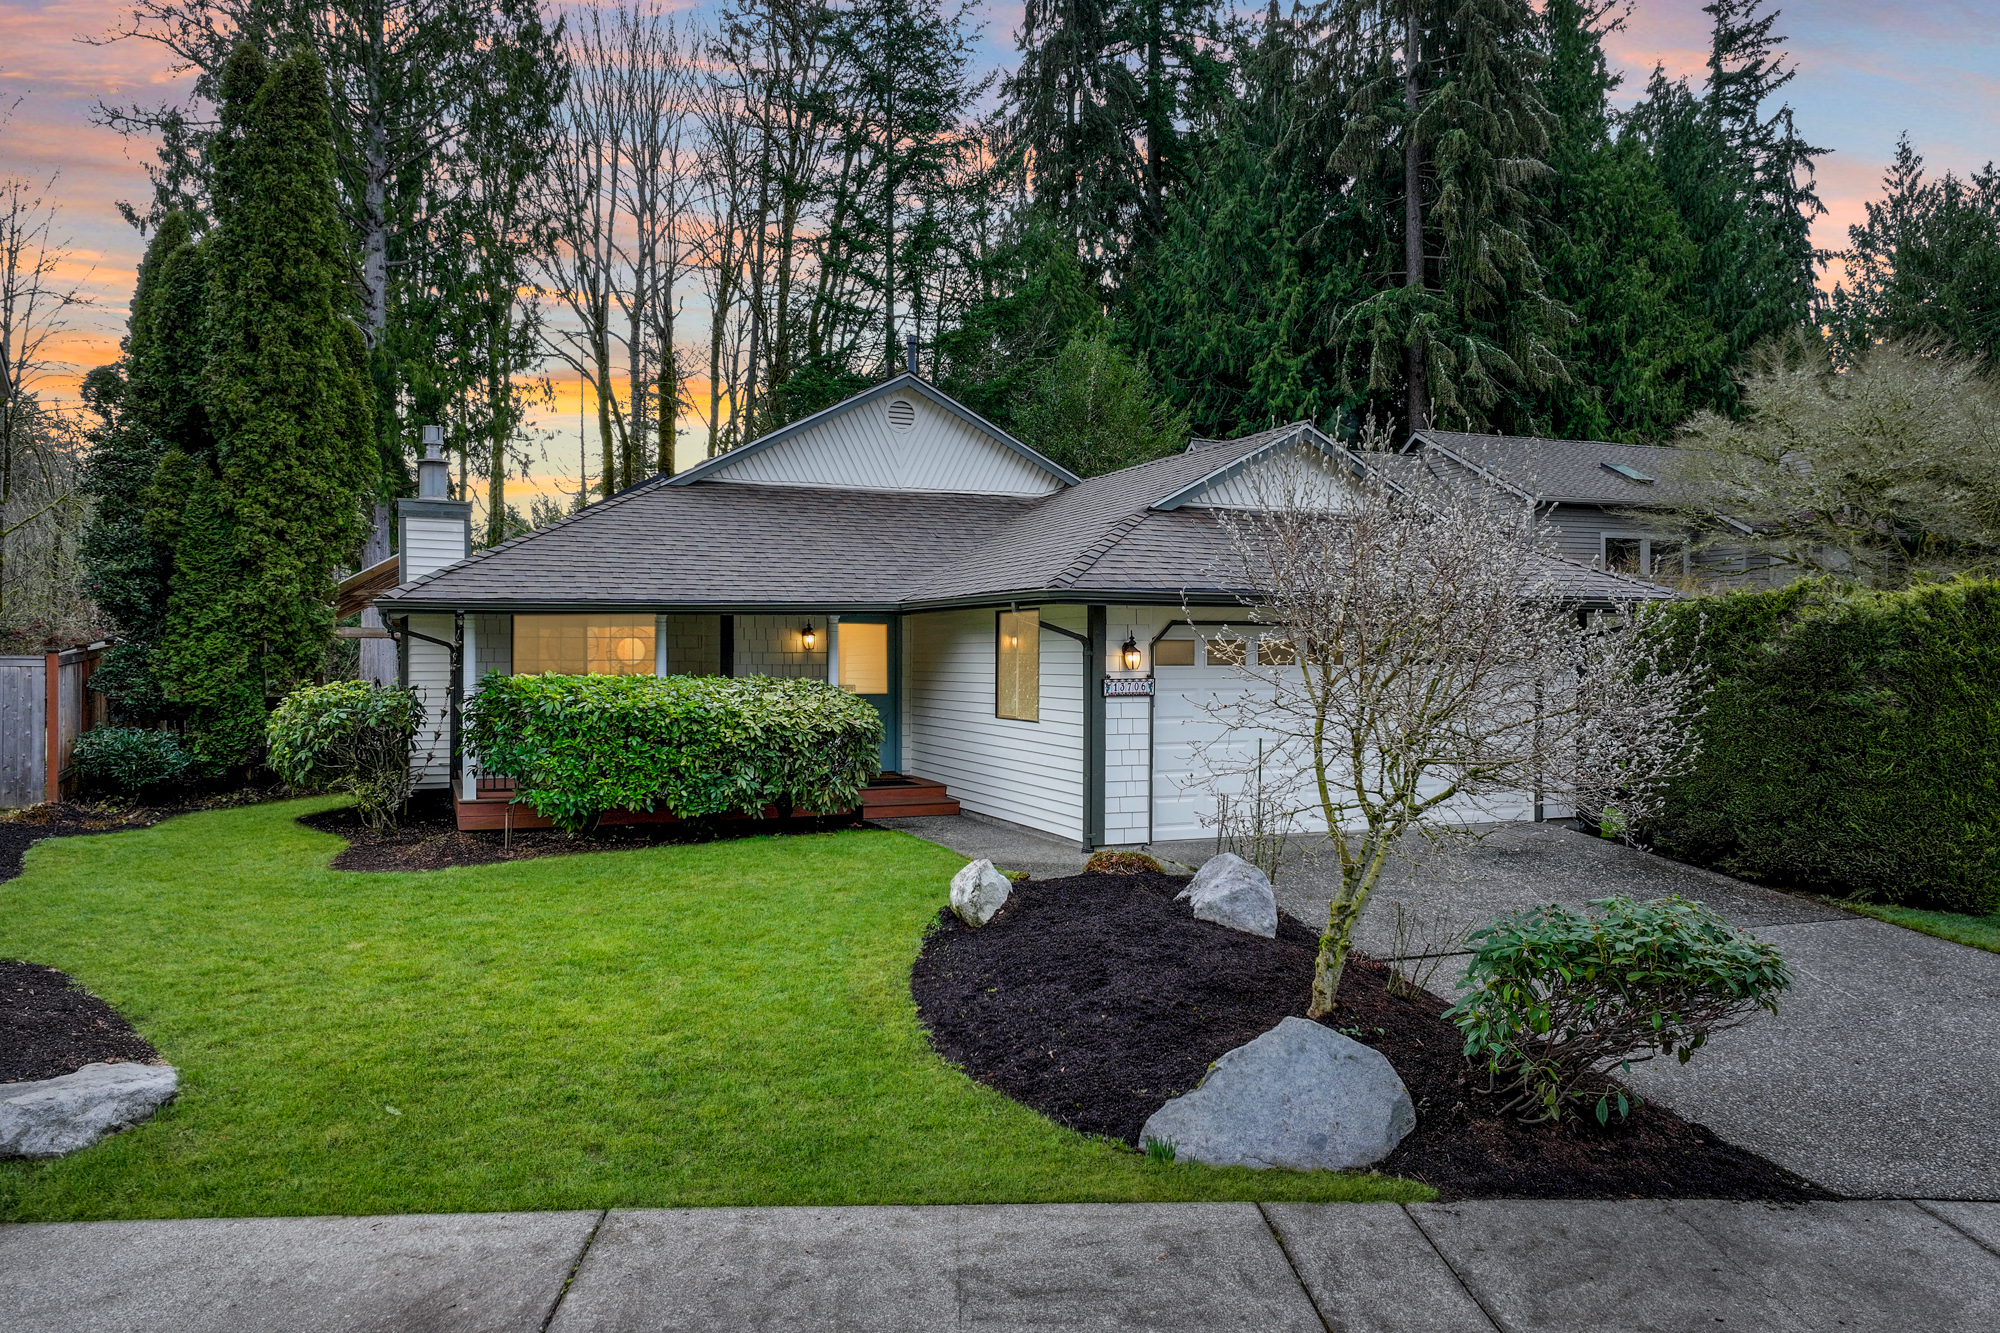
Tony Meier has represented us as both a buyer and a seller in English Hill this year. As we...

For over 20 years, Tony, Wendi, and Rachel have been our trusted friends and neighbors—but...

I had the pleasure of working with Tony Meier to sell my English Hill home. Tony took the time...
Thank you so much for all your help and support in the home buying process. Your care, kindness...

Thank you for the team ! "Excellent reputation in the real estate business, reliability and...
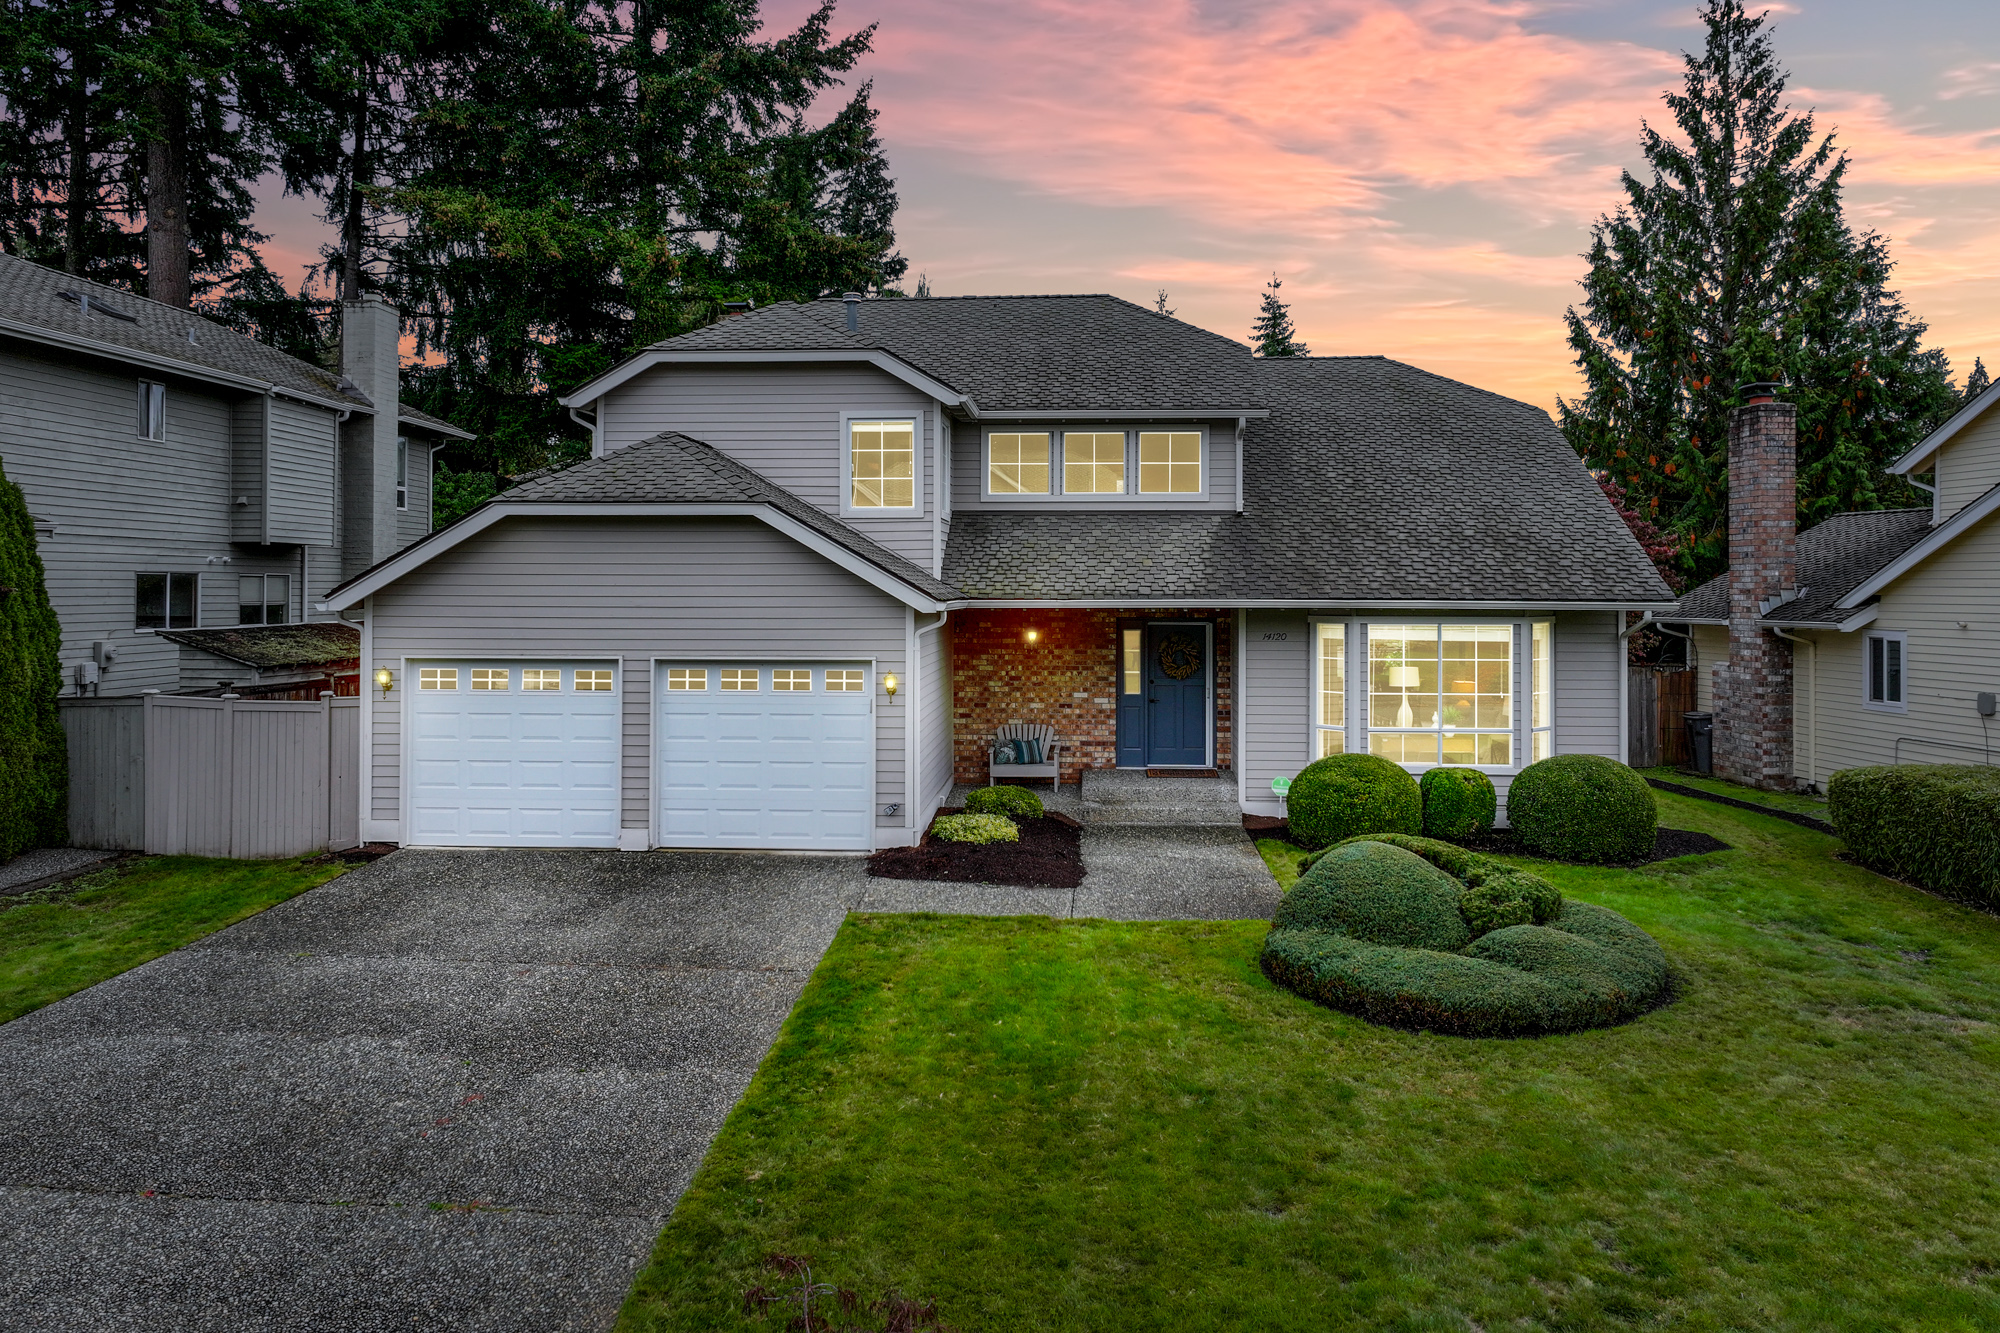
Selling our home in English Hill was a major milestone, and we couldn’t be happier that we...

We have used Tony Meier for two home purchases, and one home sale (and currently working with him...

“Tony and team made our first home buying experience extremely smooth and stress free. His...

"Tony and his team are amazing. Trust what he tells you and do what he says. We did the changes/...

"Tony Meier and Team were extremely helpful in selling our home quickly and efficiently within a...

"It's never easy to say goodbye to a house full of memories and a neighborhood you love. But when...

"My husband Rob and I have always known we would use Tony & his team when the time came to sell...

"We are thrilled to express our gratitude to Tony for his exceptional guidance in our first home...
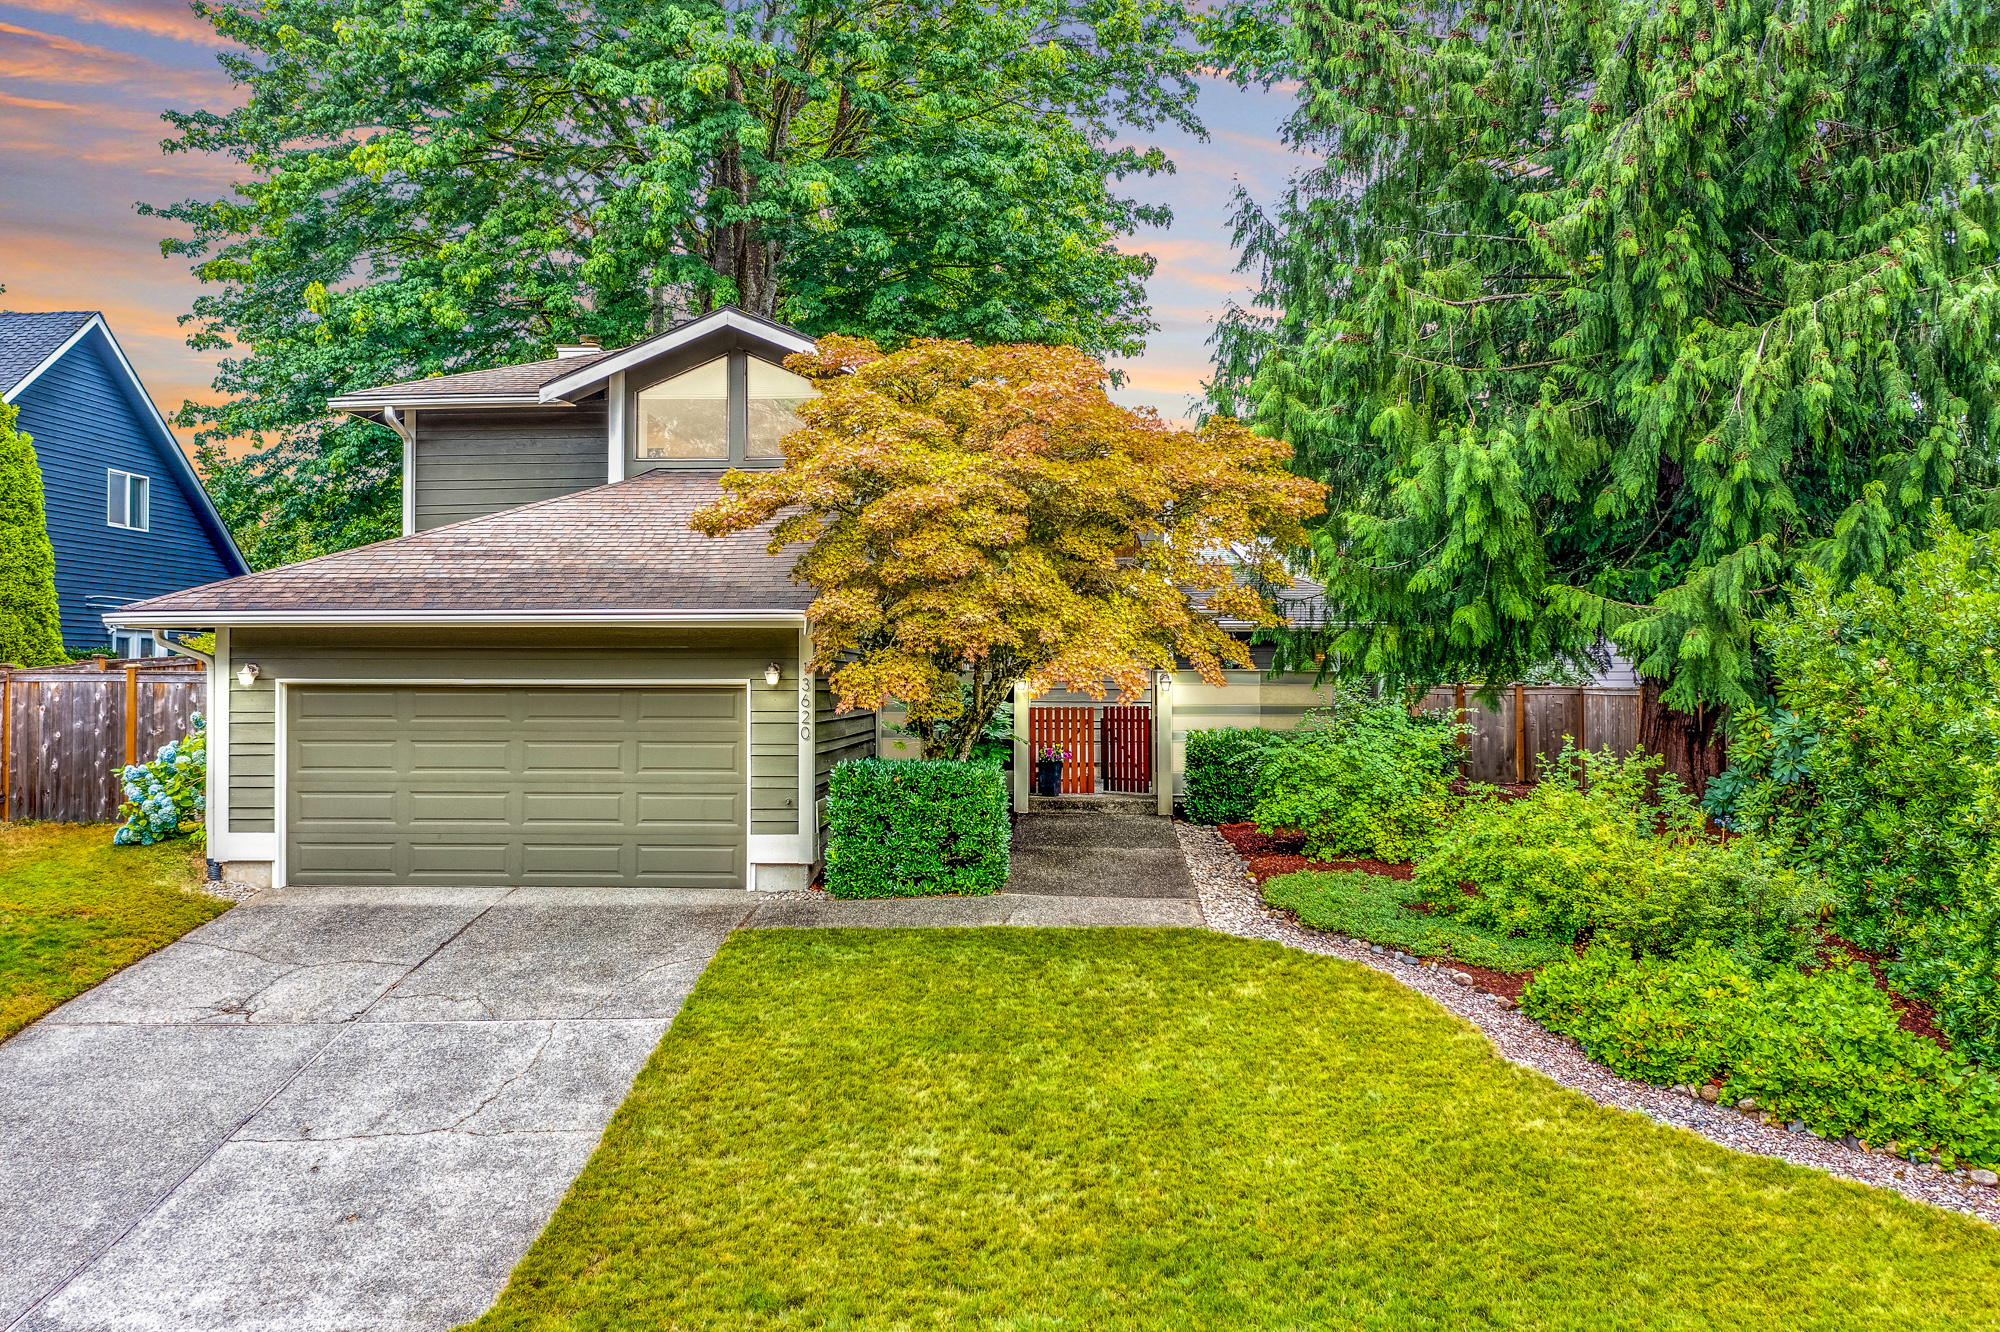
"Tony and Team provided us with resources and support for a smooth and pleasant property sale of...

"Tony and his team made the process of selling our house as easy as it could possibly be. He had...
"Tony and his team did an amazing job in helping us sell our home. Tony has a deep understanding of...
Compare listings
Compare